Quick answer
For ATO debt help in Sydney, contact the ATO before the debt escalates, check whether you also owe Revenue NSW for payroll or land tax, and use free help such as the Small Business Debt Helpline and the NSW Small Business Commissioner. If one payout beats juggling plans, we lend to Sydney businesses from $20k to $5m, including loans secured over property in New South Wales.
Key points
- Revenue NSW says employers who can't pay payroll tax in full may be eligible for an instalment plan.
- Revenue NSW has a separate tax debt team for amounts already overdue.
- The NSW Small Business Commissioner offers guidance and low-cost mediation for disputes, such as a client who won't pay.
- Professional services and construction firms often owe PAYG withholding as well as GST.
- We lend Australia-wide; property-secured loans can be over residential or commercial property in NSW.
Why do so many Sydney businesses fall behind with the ATO?
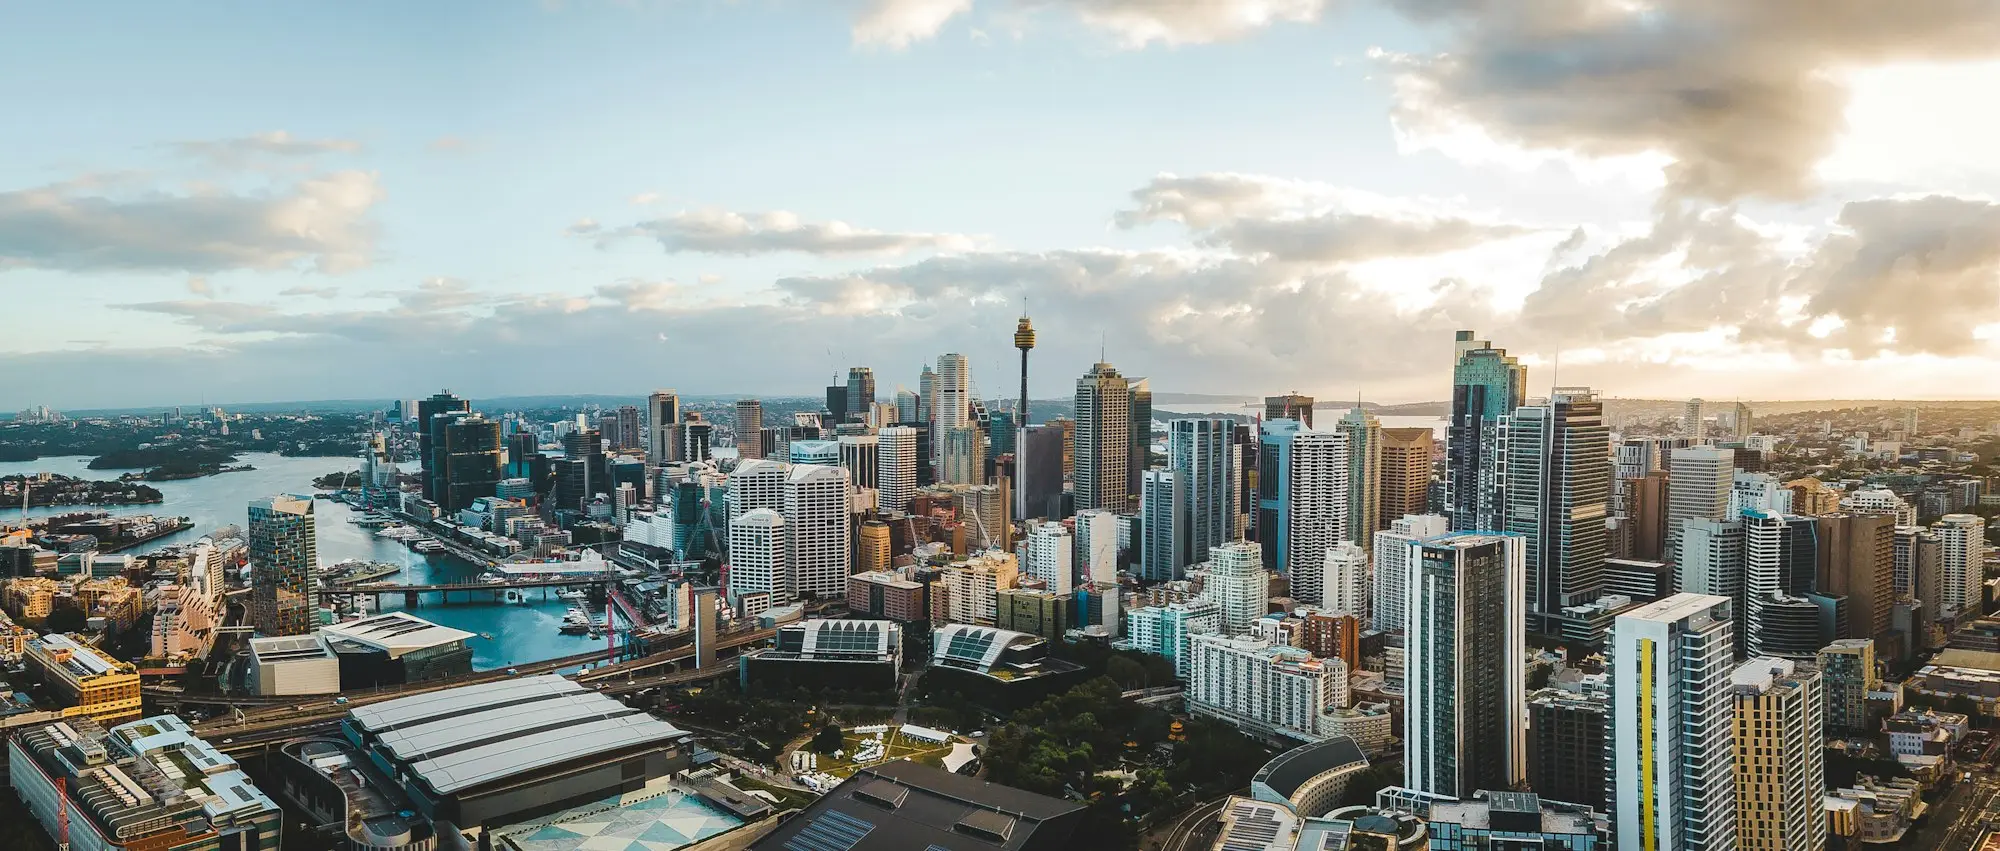
Sydney is an expensive place to run a business. Rents in Parramatta, North Sydney and the CBD are high, wages are high, and many firms are paid by large corporate or government clients on long terms. When a quarter goes badly, the tax office is the creditor that doesn’t ring every morning, so it gets paid last. That’s understandable, but it’s also how a manageable BAS shortfall becomes a six-figure problem.
ATO debt help for a Sydney business should start with a clear-eyed list of what you owe, then work through the cheap fixes before anything expensive. The order matters, and so does the New South Wales layer of state tax that sits on top of the federal one.
What state taxes do NSW businesses owe on top of the ATO?
Revenue NSW collects payroll tax and land tax. It is a state agency with its own collection and recovery process, completely separate from the ATO.
- Payroll tax applies once your total Australian wages pass the NSW threshold. Growing professional firms are often caught off guard when a hiring round tips them over, because the first liability arrives on top of an already stretched cash position.
- Land tax is assessed each year on land you own above the threshold, excluding your principal place of residence. Owners who hold their office, workshop or an investment property in their own name or a related trust feel this one.
Revenue NSW says that if you can’t pay payroll tax in full by the due date, you “may be eligible for an instalment plan”, and that plans may include interest (Revenue NSW payment options). It lists a payroll tax team on 1300 139 815 and a tax debt team on 1300 368 710 for debts already overdue. If you don’t pay or make contact by the due date, interest and possibly penalty tax apply.
The practical lesson: you need two conversations, not one. An ATO arrangement won’t stop Revenue NSW, and Revenue NSW won’t wait just because the ATO is happy.
Which Sydney industries see the most tax debt?
Professional services. Consultancies, IT firms, recruiters, architects and accountants make up a large share of Sydney businesses. They rarely lack revenue; they lack timing. Salaried staff are paid fortnightly, while invoices to corporate clients take 30, 60 or 90 days. PAYG withholding builds fastest here, and that debt can follow directors personally. Our guide to PAYG withholding debt explains the exposure.
Construction. From apartment towers to suburban renovations, Sydney’s building sector runs on progress claims. Subcontractors in Western Sydney often carry GST on invoices they haven’t been paid for yet, which is a cash drain that doesn’t show up on the profit and loss.
Hospitality and retail. Inner-city venues and suburban strip shops deal with high rent and thin margins. A slow winter can push a café two quarters behind on BAS before the owner notices.
What free help is available in New South Wales?
Start with the free options. They cost nothing and some will make any later funding cheaper.
| Service | What it does | Contact |
|---|---|---|
| Small Business Debt Helpline | Free, independent financial counselling for small business owners | 1800 413 828 |
| NSW Small Business Commissioner | Guidance, one-on-one help and low-cost mediation for disputes with clients, landlords or government agencies | 1300 795 534 |
| Revenue NSW payroll tax team | Instalment plans for payroll tax you can’t pay in full | 1300 139 815 |
| ATO | Payment plans and, in some cases, interest remission | Online or by phone |
The NSW Small Business Commissioner is especially useful when the reason you can’t pay the ATO is that someone else isn’t paying you. It describes its mediation as low-cost and handles disputes involving commercial leases, contracts with government agencies, contractors and franchises (business.gov.au). Recovering a stuck invoice can be cheaper than borrowing.
On the federal side, read up on ATO payment plans and GIC remission before you call, so you know what to ask for.
Illustrative example: a Sydney engineering consultancy
A made-up scenario with round amounts, to show the decision rather than any real client.
A structural engineering consultancy in North Sydney employs 25 people. It wins a large government infrastructure job, hires six engineers to deliver it and crosses into payroll tax. Then the client’s approval process stalls and two milestone payments slip by four months.
By the time the money is confirmed, the firm owes the ATO around $320k across GST and PAYG withholding, and Revenue NSW about $60k in payroll tax. The ATO has started issuing reminders, and the bank has mentioned a garnishee notice it received for another client, which rattles the directors. Our page on garnishee notices explains what that can mean for a business account.
The directors have three choices: a long ATO plan plus a Revenue NSW instalment plan, a loan secured over the commercial strata office the firm’s related trust owns in Chatswood, or a combination. They request a quote and compare it line by line with the plans. Because the milestone payments are now contracted and close, a short secured loan that clears both tax creditors in one go, and is repaid when the milestones land, is simpler and protects the directors from personal exposure on the PAYG. A different firm with no confirmed income might reasonably choose the plans instead.
If you’d like to see whether a structure like this fits you, start a quick enquiry. It takes about a minute.
How does our funding work for Sydney businesses?
We lend to businesses in every state, and Sydney owners are among the most common callers. What we offer:
- Secured business loans from $20k to $5m, including first mortgages, second mortgages and caveat loans, over residential or commercial property in Sydney, the Central Coast, the Illawarra or anywhere else in New South Wales.
- Cash-flow and unsecured facilities for trading businesses, usually $5k to $500k, based on turnover and bank statements.
- A willingness to look at existing ATO debt, a defaulted payment plan or past credit trouble on its merits.
- For property-secured loans, funding is possible in as little as 24 hours, and money can go directly to the ATO when that’s arranged at settlement.
Loans are for business purposes only. We don’t run a shopfront in Sydney, so you won’t be asked to come in; a specialist handles everything over the phone. For bigger balances, our page on large ATO debt funding goes into more detail.
What if your Sydney property is already heavily mortgaged?
High Sydney property values cut both ways. Many owners have strong equity on paper, but a large first mortgage already sits over the home. In that case a second mortgage or a caveat loan behind the existing lender can sometimes unlock enough to clear the ATO without refinancing the whole home loan. Whether it works depends on the value, what’s owed and the plan to repay. Our page on refinancing ATO debt explains the difference between topping up and adding a second-ranking loan.
A simple plan for the next seven days
- Pull your ATO statement and any Revenue NSW notices into one list.
- Lodge anything outstanding; lenders and the ATO both look at this first.
- Call the Small Business Debt Helpline if you want a free, independent view.
- If a client dispute is the root cause, ask the Small Business Commissioner about mediation.
- Ask the ATO and Revenue NSW what plans they’d accept, then get a funding quote and compare total cost.
Ready to find out what your Sydney business can do?
We help owners who are behind with the tax office every week, and we don’t treat an ATO balance as a reason to say no. An enquiry takes about 60 seconds and your credit file isn’t touched just for asking. Your details aren’t sent around a pile of lenders either, so you won’t be swamped with calls. A specialist looks at your specific situation and rings you. Please fill the form in accurately, including any Revenue NSW debt, so the first conversation is a useful one.
Prefer to read more first? See ATO debt help in other cities or our main guide to tax debt loans.
Frequently asked questions
Who can help with ATO debt in Sydney for free?
The Small Business Debt Helpline (1800 413 828) offers free financial counselling to small business owners nationally, including in Sydney. The NSW Small Business Commissioner (1300 795 534) gives guidance and low-cost mediation if a dispute, such as an unpaid invoice, is behind the cash shortfall. You can also negotiate with the ATO directly.
Can I get a payment plan for NSW payroll tax?
Revenue NSW says you may be eligible for an instalment plan if you can't pay payroll tax in full by the due date, and that such plans may include interest. Contact its payroll tax team as soon as possible; if the debt is already overdue, there is a separate tax debt team.
Can a Sydney business borrow to pay the ATO?
Yes. We fund businesses Australia-wide from $20k to $5m. Loans can be secured over residential or commercial property in Sydney or regional NSW, and unsecured options exist for trading businesses with steady turnover.
Do I need to meet you in Sydney?
No. We don't have a Sydney office. Everything is done by phone and online, and a specialist calls you after you enquire.
Is a debt to Revenue NSW treated differently from ATO debt?
Yes. They are separate creditors with separate powers, so an ATO plan doesn't pause Revenue NSW and the reverse is also true. Each needs its own arrangement or payout.
Sources
Facts on this page were checked against official sources on 4 October 2026. Rules and thresholds change, so confirm anything critical on ato.gov.au or asic.gov.au.